Corporate Analysis of Deutsche Lufthansa’s Expanded F‑35 Acquisition
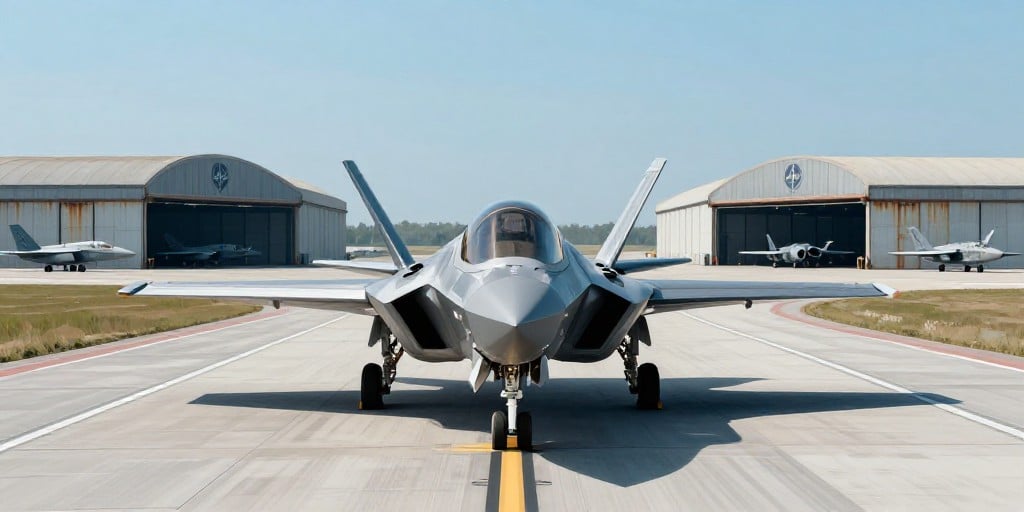
Deutsche Lufthansa’s latest procurement decisions underscore a broader strategic shift within the German defence sector. The acquisition of additional F‑35A stealth fighters, which have already entered operational service under the national emblem, marks a decisive move to replace the aging Tornado fleet. This development is not merely a tactical upgrade; it reflects a recalibration of Germany’s defence posture, industrial policy, and its role within the broader NATO framework.
Operational Capability versus Domestic Manufacturing
The introduction of the F‑35s enhances Germany’s tactical flexibility, particularly with respect to nuclear sharing obligations. These aircraft are specifically configured to transport U.S. nuclear weapons stored at German bases—an operational role that the Tornado fleet will relinquish by 2030. While the first F‑35 has already proven its operational value, the decision to procure further jets raises an important debate: how to balance expanded operational capability against the preservation of domestic manufacturing expertise.
Rheinmetall’s contribution to the production of airframes demonstrates that Germany can retain a meaningful role in the supply chain. However, critical components—engines, sensors, and flight‑control systems—continue to be supplied by U.S. vendors. This reliance limits the potential for a fully German‑made platform and constrains the country’s ability to develop an indigenous fifth‑generation fighter within the short term.
Implications for German Defence Industry
Industry observers argue that continued dependence on U.S. technology could hinder Germany’s ambition to establish a sovereign fifth‑generation fighter capability. Nevertheless, the German defence ministry is actively pursuing partnerships that could enable greater maintenance and software integration within a German consortium. By doing so, Germany may gradually reduce its dependence on external suppliers while simultaneously strengthening its domestic industrial base.
These dynamics are reflective of a broader European trend. The F‑35 programme serves as a barometer for the future direction of European defence manufacturing and procurement, highlighting the tension between multinational collaboration and the pursuit of national industrial autonomy.
Broader Market Context and Organizational Change
Deutsche Lufthansa’s parent company is concurrently navigating significant workforce restructuring and technological integration. This parallel shift illustrates a wider trend of organisational change within German industry, driven by the need to adapt to evolving market conditions, technological advancements, and global supply chain disruptions. The alignment of the airline’s operational priorities with the defence sector’s procurement strategies signals an integrated approach to resource allocation and technological capability development across sectors.
Conclusion
The expansion of the F‑35 fleet represents a critical juncture for Germany’s defence strategy. While the acquisition offers immediate operational advantages and aligns with NATO nuclear sharing obligations, it also exposes the limitations of current domestic manufacturing capabilities. Continued investment in German partnerships aimed at enhancing maintenance and software integration could mitigate these limitations over time. As such, the F‑35 programme not only shapes Germany’s military readiness but also serves as a key indicator of the future trajectory of European defence manufacturing and procurement.