Commerzbank AG Strengthens Position Through Rating Endorsement, Capital Relief, and Market Confidence
Commerzbank AG has recently demonstrated a consolidated financial footing, as evidenced by a sequence of favorable developments that span credit ratings, regulatory capital requirements, and market performance. The interplay of these factors reinforces the bank’s resilience and suggests a continued capacity to support growth while delivering value to shareholders.
Credit Rating Confirmation and Integration Context
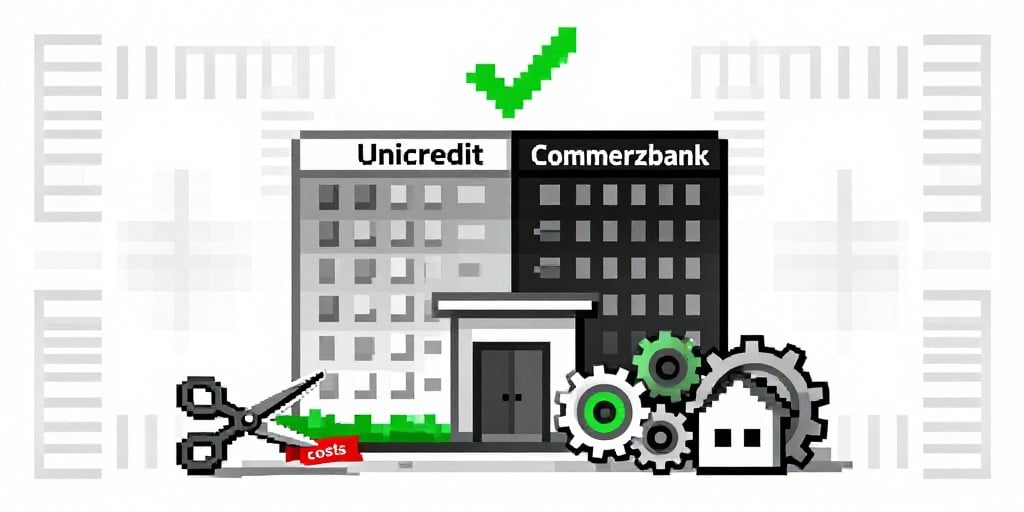
On 27 October, the German rating agency Scope reaffirmed Commerzbank’s A‑rating with a stable outlook. Scope cited the bank’s robust operating performance and a solid solvency and refinancing profile as the primary basis for the confirmation. Importantly, the agency highlighted the ongoing integration with Unicredit, noting that the merger process does not materially alter the credit assessment. The endorsement serves to validate the bank’s risk‑adjusted profitability and capital adequacy, thereby sustaining investor confidence.
Capital Relief from the ECB’s SREP
In its latest Supervisory Review and Evaluation Process (SREP) update, the European Central Bank (ECB) announced a further reduction in Commerzbank’s capital requirements for 2027. The Pillar 2 capital requirement was cut by five basis points to 2.10 % of total capital, while the pro‑forma Common Equity Tier 1 (CET 1) threshold at the group level settled at 10.26 % of risk‑weighted assets. This represents the second consecutive year of regulatory easing and indicates a deliberate effort to preserve a comfortable capital buffer while maintaining the bank’s capacity to fund growth initiatives and return capital to shareholders.
Financial analysts note that such capital relief is not merely a cost‑saving measure; it also improves the bank’s risk‑adjusted return on equity (ROE). By lowering the CET 1 threshold, the ECB effectively reduces the amount of capital that must be held against the bank’s risk‑weighted assets, thereby freeing resources that can be deployed in lending or capital returns.
Market Reaction and Index Impact
On the Frankfurt exchange, Commerzbank’s shares advanced in a broader rally that lifted the LUS‑DAX index. The bank’s stock was among the top performers that session, delivering a modest price increase that nonetheless contributed to the index’s overall gains. As of the end of the trading day, the LUS‑DAX had recorded a year‑to‑date rise exceeding 4 %, a figure that benefits from the positive momentum surrounding major financial institutions.
While the price uplift for Commerzbank was modest relative to its market capitalization, the upward movement signals market endorsement of the bank’s improved fundamentals. Analysts caution that short‑term price dynamics should be interpreted in light of the longer‑term structural factors—namely, the stable rating, regulatory capital relief, and resilient operating metrics—that underpin investor sentiment.
Underlying Business Fundamentals and Competitive Dynamics
A deeper examination of Commerzbank’s business model reveals several layers of resilience:
Diversified Revenue Streams: The bank continues to benefit from a balanced mix of retail, corporate, and investment banking activities. Its exposure to the German corporate sector remains strong, providing a stable income base that can weather regional economic fluctuations.
Cost Efficiency Initiatives: Recent cost‑saving measures, particularly those stemming from the Unicredit integration, have lowered operating expenses. These efficiencies help sustain net interest margins even amid tightening regulatory requirements.
Digital Transformation: Commerzbank’s ongoing investment in digital platforms—especially its “Digital Bank” strategy—positions it to capture market share in the burgeoning fintech‑enabled banking segment. This transformation aligns with broader European banking trends, where digitalization is increasingly a competitive differentiator.
Risk Management Framework: The bank’s conservative approach to credit provisioning and risk concentration mitigates potential loan‑quality deterioration. This risk discipline aligns with the ECB’s emphasis on prudent capital provisioning.
Potential Risks and Opportunities
Despite the positive outlook, several risks merit monitoring:
- Regulatory Uncertainty: Future shifts in ECB supervisory standards or changes in Basel III requirements could alter capital buffers unexpectedly, affecting profitability.
- Macroeconomic Headwinds: Rising inflation and potential interest‑rate hikes in the eurozone could compress net interest margins, especially if loan demand weakens.
- Integration Challenges: While the Unicredit merger has not yet impacted the rating, lingering integration costs or cultural mismatches could surface, influencing operational efficiency.
Conversely, opportunities are apparent:
- Capital Allocation Flexibility: Reduced capital requirements grant Commerzbank greater freedom to allocate resources toward strategic acquisitions or capital return schemes.
- Market Leadership in Germany: The bank’s robust domestic footprint and regulatory compliance could position it favorably in a consolidating German banking sector.
- Fintech Partnerships: Continued collaboration with fintech firms could unlock new revenue streams and enhance customer experience, reinforcing the bank’s competitive edge.
Conclusion
Commerzbank AG’s recent rating confirmation, capital relief, and positive market reception collectively signal a stable outlook for the institution. The bank’s prudent risk management, solid operating performance, and strategic positioning within the German banking landscape continue to underpin investor confidence. While vigilance is warranted around evolving regulatory and macroeconomic factors, the current trajectory suggests that Commerzbank is well‑equipped to navigate future challenges and capitalize on emerging opportunities.